IFC launches agritech financing program for 15 African startups
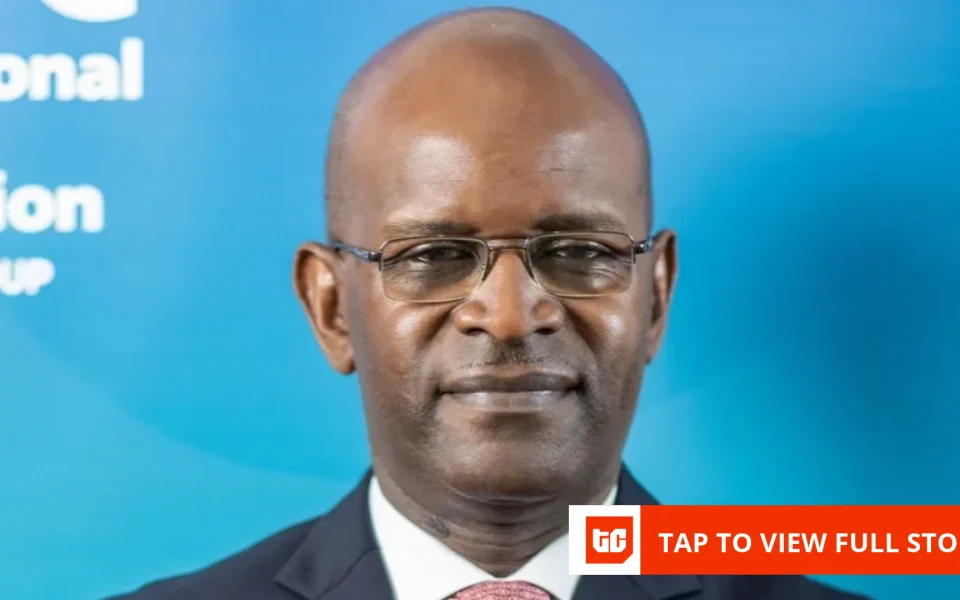
The International Finance Corporation (IFC) announced on Wednesday that it is backing a new agritech financing initiative covering 15 technology firms across Africa. Speaking at the Africa Financial Industry Summit in Luanda, Aliou Maima, director of the IFC’s Financial Institutions Group for Africa, said the programme will provide direct equity to the selected companies and connect them to a network of nearly 200 commercial banks through risk‑sharing guarantees. The move follows two decades of stalled attempts to modernise African agriculture with technology, and aims to shift financing away from fragile startup balance sheets toward established lenders. Maima noted that Africa imports roughly $90 billion of staple foods each year, a cost that fuels inflation and pressures central banks’ interest‑rate policies.
Under the new framework, the IFC will inject equity into each of the 15 agritech firms to help them finish product development and scale operations. Rather than forcing these startups to raise costly debt to lend directly to farmers, the programme links them to the IFC’s broad banking network, allowing commercial lenders to provide credit from their own balance sheets. Guarantees from the IFC will absorb a defined share of eligible loan losses, reducing the risk banks face when extending loans to smallholder farmers. Maima explained that this tripartite model separates the roles of technology provider, lender and risk‑sharer, a departure from earlier venture‑capital‑driven approaches that left startups bearing the full credit exposure.
The selected agritech companies will act as digital origination and field‑management platforms. Their technology will identify eligible farmers, collect agricultural data, assess risks and coordinate last‑mile services through community‑based agents. These agents, recruited locally, carry connected handheld devices that can diagnose soil conditions, monitor weather impacts, schedule fertiliser applications and track crop health. By translating field observations into actionable data, the platforms aim to improve yields, with the IFC citing cases where productivity has risen by up to 50 percent.
Commercial banks participating in the scheme will use the data and farmer‑origination support supplied by the agritech partners to evaluate loan applications. Once approved, banks will disburse credit directly from their own balance sheets, retaining the credit risk but benefiting from the IFC’s portfolio guarantees. The guarantees do not eliminate the bank’s exposure entirely; instead they cover an agreed portion of qualifying losses, offering a safety net that encourages lenders to extend credit to previously underserved rural producers. The exact percentage of risk covered was not disclosed in the briefing.
Maima stressed that the success of the programme hinges on more than capital flows. “Our approach is to combine technology with agents on the ground, usually recruited from the communities where farmers operate,” he said. He added that pure‑play digital platforms have limited reach because many smallholders lack reliable connectivity or digital literacy. The hybrid model of mobile tools and physical agents is designed to bridge that gap, ensuring that farmers receive both financial resources and practical agronomic advice.
Beyond the private‑sector mechanics, the IFC is seeking alignment with national and regional policies to remove regulatory bottlenecks. The corporation is integrating the agritech framework into broader state initiatives, including a flagship agricultural programme launched with the Nigerian government and ongoing negotiations with sub‑national administrations in other key markets. These sovereign agreements are intended to set production targets, guarantee access to infrastructure and streamline regulations across the value chain. Maima indicated that once such commitments are in place, the IFC will coordinate with farmer cooperatives, agritech platforms and commercial lenders to track disbursements and measure impact on yields.
The macro‑economic rationale behind the effort is clear. Reducing reliance on imported staples such as rice, wheat and sugar can help temper food‑price inflation, a major driver of consumer‑price indices in Sub‑Saharan Africa. Lower food inflation, in turn, eases monetary pressure on central banks, potentially moderating benchmark interest rates. By boosting domestic agricultural productivity, the programme seeks to create jobs, enhance food security and contribute to more stable macro‑economic conditions across the continent.
While the initiative marks a strategic maturation for Africa’s agritech sector, several uncertainties remain. The IFC did not disclose the total credit volume expected to be deployed, the number of banks that will ultimately participate, or the precise number of smallholders the programme will reach. Moreover, the effectiveness of the risk‑sharing guarantees will depend on the banks’ underwriting standards and the quality of data supplied by the tech firms. Critics have warned that without robust monitoring, the promised yield gains may not materialise at scale.
Nonetheless, the launch of this agritech financing programme represents a concerted effort by a major development finance institution to address long‑standing obstacles in farm financing. By aligning startup innovation, bank capital and government policy, the IFC hopes to transform smallholder agriculture from a high‑risk sector into a viable investment opportunity. The next step will involve rolling out the first batches of loans through participating banks, with Maima promising regular updates on farmer outcomes and the programme’s broader impact on Africa’s food‑security landscape.

Join the conversation