African Payment Switches Push for Sovereign Cross‑Border Network
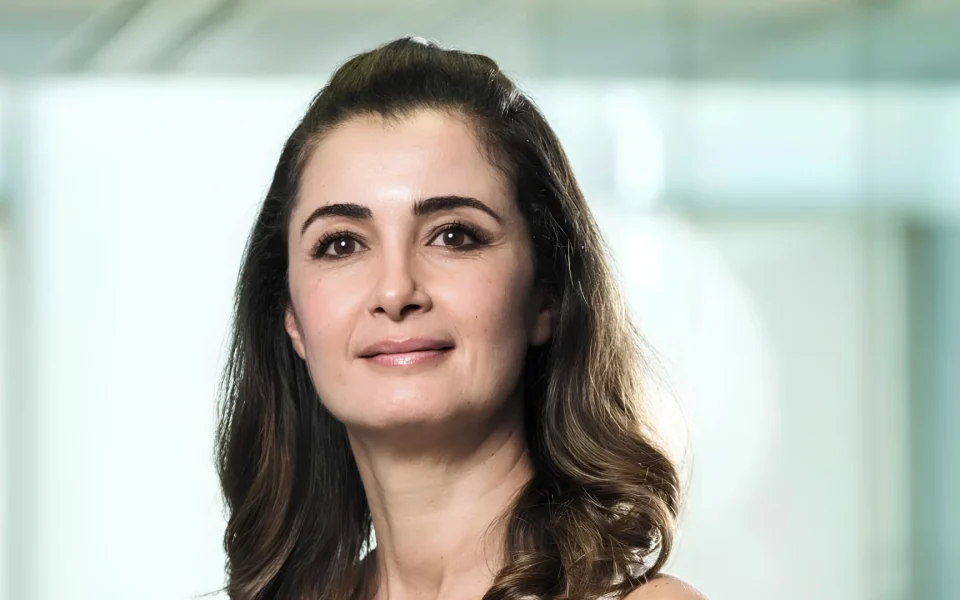
The Managing Director of Morocco’s Switch Al‑Maghrib, Hanae Ben Driss, told reporters that “sovereignty is not negotiable” as she made the case for a continent‑wide network of african payment switches. Speaking on the sidelines of an industry gathering, Ben Driss argued that what outsiders label as fragmented national payment rails are in fact the first step toward financial self‑determination for African states. She recalled Morocco’s own journey, where a domestic interbank switch went live around 2005, allowing local card transactions to be settled without recourse to international schemes. The conversation then turned to how this model can be replicated, linking digital wallets rather than traditional cards, and how Switch Al‑Maghrib is already engaging peers in Nigeria, Ghana, Rwanda and Angola to form an association of african payment switches.
Ben Driss stressed that the prevailing view of fragmentation overlooks the strategic need for each country to own its critical infrastructure. “Every country needs to have sovereign control over its critical infrastructure,” she said, noting that sovereignty does not require every nation to develop every component from scratch. Instead, the emphasis is on retaining control over the evolution and management of systems that underpin the digital economy. She warned that reliance on offshore multinational actors leaves African economies vulnerable to external shocks and to objectives that may not align with national priorities. While Europe and the United States have pursued top‑down integration, she pointed out that Africa lacks a comparable political framework, making a bottom‑up approach, building domestic switches first and then interconnecting them, a more realistic pathway.
The practical aim of the proposed association of african payment switches is to create a technical framework that bypasses lengthy political treaties. Ben Driss said Switch Al‑Maghrib is already in contact with national switches in several countries and is “progressively building relationships” to facilitate interoperability. The focus is on connecting payment infrastructures rather than establishing a continental regulatory regime akin to the European Union. She stressed that isolated markets risk falling behind as artificial intelligence and agentic commerce reshape global finance. “Even Europe is struggling to achieve technological independence against the United States and China,” she warned, adding that African switches must collaborate now to avoid irrelevance.
A key part of the strategy involves prioritising mobile wallets over traditional card networks for cross‑border transactions. Ben Driss pointed out that card schemes such as Visa and Mastercard are bound by rigid rules, high interchange fees and entrenched clearing hubs, making seamless continental payments difficult. In contrast, wallets offer greater autonomy to link ecosystems directly, enabling instant account‑to‑account transfers that sidestep international clearing rails. She stressed that technology accounts for only about 20 percent of the challenge; the larger obstacles lie in regulatory execution and domestic priorities, such as the dominance of cash in informal economies. To address security concerns, Switch Al‑Maghrib has integrated AI‑driven fraud scoring into its national routing engine, sharing the cost of sophisticated cyber‑defence across all connected institutions.
Beyond the technical angle, Ben Driss highlighted the broader purpose of a sovereign payment ecosystem. While policymakers often tout the number of newly opened bank accounts as a metric of progress, she argued that true financial inclusion requires a digital financial record, whether from a bank account, a payment account or a wallet, to build credit histories and reduce poverty. She noted that cash remains dominant because many traders view physical notes as immediate and fee‑free, and because digital transfers can expose incomes to tax authorities without a corresponding increase in public services. “We cannot simply expect merchants to change their behaviour,” she said, emphasizing the responsibility of infrastructure providers to make digital payments attractive through safety, convenience and cost advantages.
The Moroccan switch’s experience offers a concrete illustration. More than two decades ago, Moroccan commercial banks joined forces to build a unified domestic interbank switch. When it went live in the mid‑2000s, transactions where both cardholder and merchant were in Morocco no longer needed to route through foreign schemes, even if the card carried an international brand logo. That development reduced fees, shortened settlement times and gave the country greater control over its payment data. Ben Driss described this as an “important first step towards achieving greater sovereignty.”
Today, similar initiatives are taking shape in Nigeria, Ghana, Rwanda and Angola, but cross‑border interoperability remains painfully slow. Multilateral platforms such as the Pan‑African Payment and Settlement System (PAPSS) have laid down high‑level regulatory frameworks, yet technical operators must now take the initiative. Ben Driss said Switch Al‑Maghrib is forging direct operational ties with its peers, aiming to create a formal continental coalition that focuses on technical solutions rather than waiting for political treaties to harmonise. “The objective is to create a framework through which we can collaborate and focus on connecting payment infrastructures,” she explained.
She also warned that the race for technological independence is already under way globally. Artificial intelligence and autonomous software agents are beginning to execute transactions on behalf of users, and markets that remain fragmented risk being left behind. By linking wallets directly across borders, African switches can enable instant, account‑to‑account payments that bypass international clearing rails altogether, offering a more agile route for intra‑African commerce.
When asked why cross‑border payments remain difficult despite decades of conferences, Ben Driss dismissed technology as the main barrier. “Technology is only about 20 percent of the equation,” she said. The bulk of the challenge lies in regulatory execution, domestic priorities and the entrenched cash culture. Each country must grapple with its own fiscal realities, from tax compliance to public‑service delivery, while also finding the resources to establish cross‑border connections.
Rather than waiting for central banks to design technical frameworks, she argues that switch operators must be proactive. “Regulators are not necessarily technology experts, and that is understandable,” she noted. Infrastructure providers, she added, have the flexibility and agility to move faster, proposing pragmatic solutions to regulators and demonstrating how they can be implemented.
Looking ahead, Ben Driss called for infrastructure providers to take the initiative rather than waiting for regulators to design technical solutions. She urged switches to propose pragmatic solutions to regulators, noting that “regulators are not necessarily technology experts.” By fostering a collaborative continental association, the goal is to create a resilient payment landscape that supports financial inclusion beyond mere bank‑account counts. Ben Driss highlighted that true inclusion requires a digital financial record, whether from a bank account, payment account or wallet, to build credit histories and reduce poverty. As the association of african payment switches moves from discussion to concrete proposals, the next step will be formalising the technical framework and piloting cross‑border wallet connections among the early‑adopter countries.

Join the conversation