African banks urged to overhaul digital strategy, says CR2 chief executive
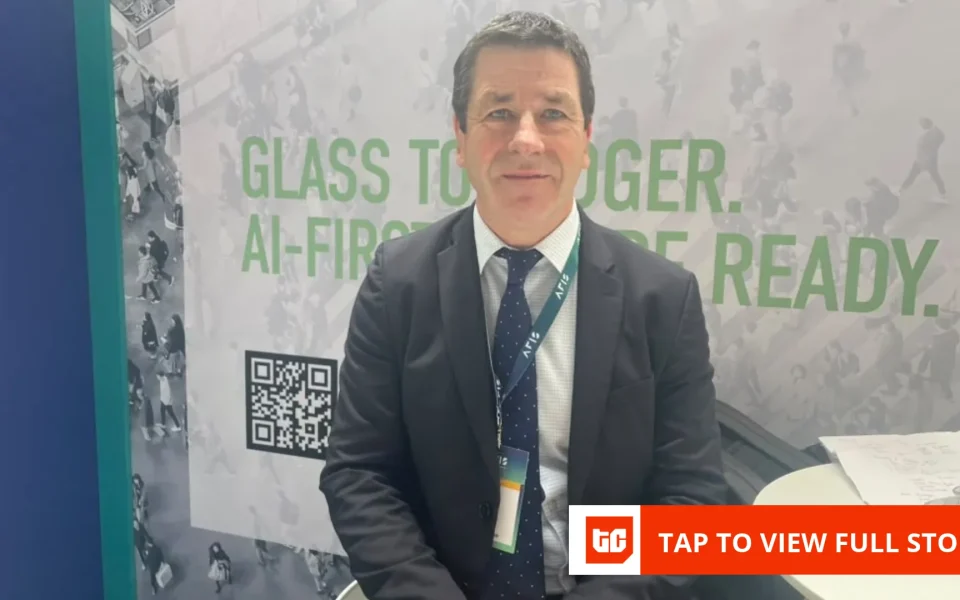
Fintan Byrne, chief executive officer of digital‑banking platform CR2, told delegates at the African Financial Industry Summit 2026 in Luanda that African banks need to rethink “digital banking africa” by moving beyond isolated mobile apps. Speaking on the sidelines of the conference, Byrne warned that banks that rely solely on a single‑purpose application risk losing market share to agile fintech rivals and failing to meet rising consumer expectations for instant, cross‑border services.
Byrne, an Irish executive with nearly three decades of experience in global payments, highlighted a decade‑long pattern in which commercial banks across the continent treated the launch of a smartphone app as the hallmark of digital transformation. He argued that this approach has become a vanity project, noting that “simply launching a mobile application does not solve any problems on its own.” The CR2 chief stressed that true innovation must be rooted in a clear value proposition, solving specific pain points and reducing friction for customers.
The speaker explained that many African lenders purchase point‑to‑point software for individual functions, onboarding, loan origination, mobile interfaces, agency banking, creating an expensive, fragmented IT estate. “One vendor is hired for customer onboarding, another for loan origination, a third for mobile interfaces, and a fourth for agency banking,” Byrne said, describing the resulting slowdown in innovation and customer frustration. His firm’s counter‑strategy, known as platformisation, involves deploying a unified architecture that allows capabilities to be switched on incrementally without overhauling core‑banking systems.
Byrne illustrated the platform approach with examples from North Africa. He cited Egypt’s Commercial International Bank (CIB), which used channel segmentation to route routine transactions away from costly branch networks toward self‑service digital and assisted channels. The shift reduced CIB’s operational cost‑to‑income ratio and accelerated customer acquisition, offering a tangible illustration of how a unified platform can deliver measurable balance‑sheet benefits.
Artificial intelligence featured prominently in the summit’s discussions, and Byrne offered a pragmatic view on its role in “digital banking africa.” He divided AI deployment into a “build phase,” where banks must design machine‑readable architectures using modern APIs and data pipelines, and a “run phase,” where AI creates commercial value through credit underwriting and fraud prevention. Referring to a market woman selling fish in Luanda or Lagos, Byrne asked how AI could better understand her cash flow and provide instant credit, noting that transaction analytics and mobile‑wallet data could replace traditional collateral in underwriting decisions.
In the run phase, Byrne said, machine‑learning models can move beyond post‑mortem transaction monitoring to predict fraudulent activity before settlement. He warned that without such proactive intelligence, banks remain vulnerable to escalating financial crime, especially as informal economies, accounting for roughly 85 % of activity, bring new risk vectors.
Beyond AI, Byrne addressed the evolving monetary landscape shaped by central bank digital currencies (CBDCs), stablecoins and tokenised assets. He argued that digital currencies should not be seen as an existential threat but as additional payment mechanisms that can coexist with legacy rails. Using an automotive analogy, he noted that electric cars did not require entirely new roads; similarly, banks can leverage existing payment infrastructure while adding charging‑station‑like capabilities for digital money.
The key to this coexistence, Byrne emphasized, is robust payment orchestration, the technical plumbing that enables seamless interaction between card schemes, mobile‑money wallets, stablecoins and traditional fiat channels. As stablecoins gain traction for cross‑border trade in currency‑starved markets, banks will need orchestration platforms that manage on‑ramps and off‑ramps, allowing customers to convert fluidly between sovereign currencies, digital tokens and bank deposits within a secure environment.
Security and regulatory compliance, Byrne warned, remain non‑negotiable foundations for any digital rollout. “The entire business of banking is built on trust,” he said, adding that security may not be the most exciting subject but is fundamental. He pointed to recent high‑profile controversies in the broader crypto sector, noting that a regulated bank losing billions of customer deposits would trigger systemic contagion and existential fallout.
Looking ahead, Byrne predicted a consolidation in how African banks engage technology providers. He expects the era of bespoke, disconnected software experimentation to give way to enterprise partnerships focused on scalability, platform resilience and hyper‑personalisation. He envisions a future where banks treat customers as “segments of one,” tailoring services to high‑net‑worth clients, mass‑affluent users, students and first‑time borrowers alike.
Byrne concluded his remarks with a clear message for the summit’s attendees: African banks that survive the next decade of disruption will be those that invest in the unglamorous, heavy‑duty platform plumbing required to orchestrate payments, automate intelligence and safeguard institutional trust, rather than those that simply launch the sleekest standalone mobile applications.
The summit, which runs through Thursday, will feature additional panels on regulatory frameworks for digital currencies and the role of fintech partnerships in expanding financial inclusion across the continent.

Join the conversation