SME lending reform urged by former Diamond Bank chief Uzoma Dozie
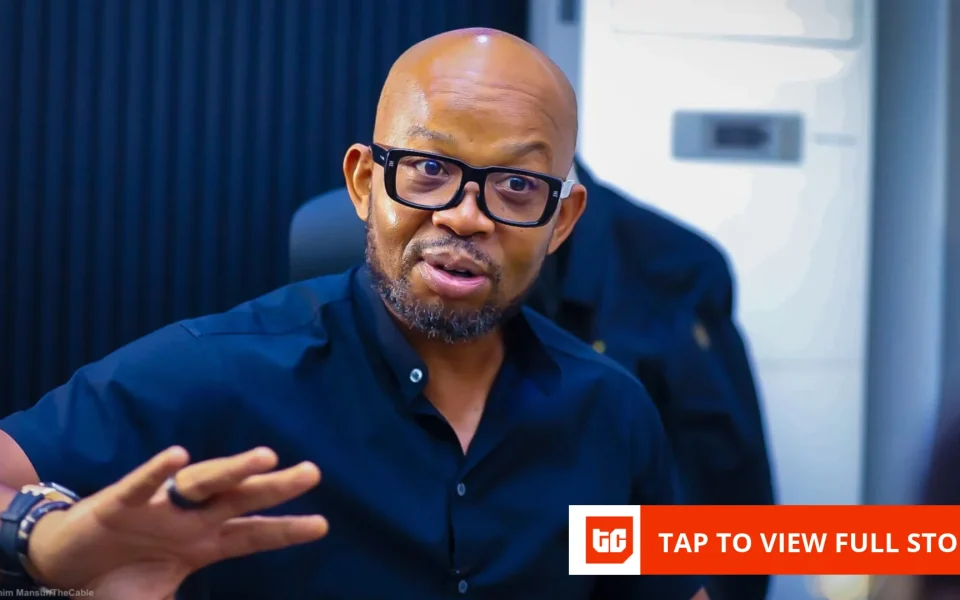
Uzoma Dozie, the former chief executive of Diamond Bank and current head of Sparkle Microfinance Bank, used his platform at the Africa Financial Industry Summit in Luanda to argue that the country’s approach to SME lending needs a fundamental overhaul. Speaking to reporters on the sidelines of the event, Dozie said that banks remain trapped by an outdated reliance on physical collateral, a practice that blocks small businesses from accessing the credit they need to grow.
Across Nigeria, small enterprises and the growing mass‑affluent segment hold a sizable portion of the nation’s deposit base, yet they receive less than one percent of total bank lending. Dozie highlighted this disparity as evidence that capital is failing to support the real economy. “Capital tends to flow towards areas of certainty, even though every investment carries some level of risk,” he explained. “What drives capital, particularly from a banking perspective, is trust. Take big businesses and large corporations: their accounts are audited and verified by professionals, so banks can lend based on information they trust.”
He contrasted the confidence banks have in large corporates with the uncertainty surrounding small firms, noting that lenders often lack sufficient information about the latter. “When you move down to small businesses and individuals, you are looking at the person. You may understand that they have a business, but you do not have sufficient information about that business. The bank either decides not to lend or lends at a price that reflects the perceived risk.”
Dozie proposed that transactional data, not physical assets, should become the new form of collateral. “Every small business generates data. Every transaction is data,” he said. “If we see data as information that can generate insights, we can use it to make credit decisions.” He argued that analysing cash flows and business‑related data could reduce risk and expand lending to sectors that currently receive little support.
The veteran banker also warned against the superficial adoption of digital‑bank buzzwords. Having overseen Diamond Bank’s merger with Access Bank, Dozie sees the current wave of digital‑only banks as repeating past mistakes. “When I hear people talk about wanting to become a digital bank, I think we have created names and buzzwords without really looking beneath the surface,” he observed. He stressed that Sparkle’s model relies on automated processes rather than a human‑touch approach, allowing the institution to serve millions without the bottlenecks of traditional account officers.
Sparkle’s focus, according to Dozie, lies with mass‑affluent individuals and small enterprises whose economic activities intersect with broader communities. He explained that an affluent Nigerian often pays several small‑business owners, creating a natural network for collective payments. “On the small‑business side, it was never just about providing a bank account. A bank account is a given because every business needs one. What was important to us was providing business support services.” By capturing transaction data, Sparkle can generate intelligence that helps businesses access credit or attract investors.
Dozie also challenged common metrics of financial inclusion that rely on the sheer number of bank accounts opened. In a country where roughly 100 million people live below the poverty line, he argued that an account without an economic purpose is merely ornamental. “If we do not solve the problems of identity and social inclusion, financial inclusion will not happen,” he said. He called for a model where government social programmes, healthcare, insurance, emergency relief, education, are channelled through formal banking rails, giving citizens a clear reason to use their accounts.
The operational reality of small businesses and households, Dozie noted, is centred on collective cash flows such as payroll, vendor payments and bulk disbursements. While many digital banks concentrate on peer‑to‑peer transfers, Sparkle has built its platform around one‑to‑many, many‑to‑one and batch transactions. “Anyone can facilitate one‑to‑one transactions,” he said, “but one‑to‑many, collective payments, and many‑to‑one transactions are areas where Sparkle specialises.” This focus, he believes, differentiates Sparkle from competitors and aligns with the real needs of Nigerian enterprises.
Artificial intelligence, Dozie added, is already moving beyond hype at Sparkle. Conversational AI tools let customers check balances and conduct routine tasks without human intervention, cutting administrative costs. More importantly, machine‑learning algorithms analyse internal cash flows, matching payment patterns with market dynamics to build richer financial profiles than traditional paper statements can provide. “Internally, AI allows us to use customers’ cash flows to identify insights and correlations between their payments, their markets, and their business activities,” he said. “We can then use that information to make better credit decisions. This helps us reduce the cost of lending and potentially offer credit at lower interest rates than would ordinarily be possible through traditional lending models.”
Dozie also highlighted how AI‑driven insights benefit merchants directly. By granting access to operational data, Sparkle can advise businesses on performance trends and customer behaviour, creating a two‑way value exchange. “They give us access to their data, and we use it to provide insights that help them make better decisions,” he remarked. “At the same time, we use that information to make better decisions about how we serve them and grow alongside their businesses.”
As the summit concluded, Dozie called on regulators and fellow banks to reconsider the definition of collateral and to adopt data‑centric lending models. He stressed that the sector must move beyond counting accounts and focus on integrating identity, social support and transactional intelligence into the financial system. The next steps, he indicated, involve piloting AI‑enabled credit scoring tools across Sparkle’s client base and working with policymakers to embed these approaches into broader financial‑inclusion strategies.
The conversation at AFIS show a growing consensus among industry leaders that leveraging technology and data could unlock the credit needed by Nigeria’s small‑business sector, potentially reshaping the nation’s economic landscape.

Join the conversation